DocSend publishes an annual study of how investors read pitch decks that tracks time-on-slide, page-by-page engagement, the correlation between specific slides and whether a founder receives a follow-up meeting. It is one of the few pieces of data in the fundraising world that goes beyond what investors say they want and looks at what they actually do when a deck is in front of them. The results are consistently surprising to founders and consistently unsurprising to anyone who has read a lot of decks.
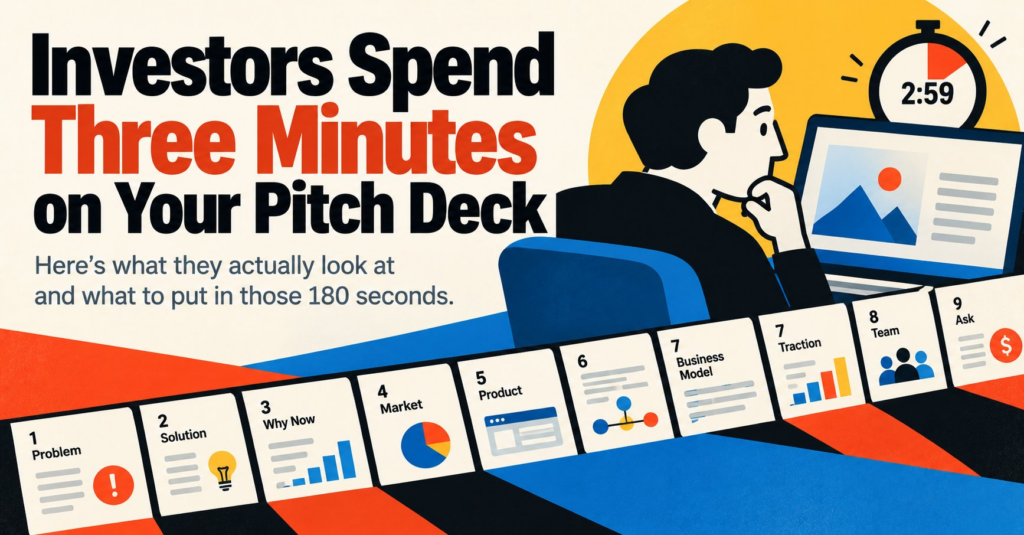
The headline finding from recent versions of the study: the average investor spends under three minutes on a pitch deck before deciding whether to continue. That number tends to produce two responses from founders. Some find it discouraging because its years of work compressed into 150 seconds. Others find it clarifying. If three minutes is what you have, the question becomes what those three minutes should contain.
Where investors spend time — and where they do not
The slides that consistently attract the most investor attention in the DocSend research are the team slide, the financials, and the product. The problem and solution slides receive less time than founders typically invest in writing them not because investors do not care about the problem, but because experienced investors form a preliminary view of the problem quickly and move on to what they consider harder questions: who is building this, do the numbers make sense, and does the product actually exist.
Make your three minutes count. VentureFactory helps you build an investor pitch backed by real business evidence. Start free.
The traction slide, when it exists, tends to command serious attention. Investors examining a deck with early revenue data or user growth numbers spend meaningfully more time on that slide than on the narrative sections. The implication for founders is straightforward: if you have any evidence of market response like paying customers, consistent retention, a waitlist that converted above the baseline, that evidence belongs prominently in the deck, not buried in the appendix.
The competitive landscape slide is worth particular examination, because it is the one where the gap between what founders include and what investors want to understand is widest. Most founders present a two-by-two matrix positioning their product favourably against named competitors. Most investors use this slide to assess whether the founder understands the actual competitive dynamics of their market which is a considerably more nuanced question than which quadrant a company sits in. A competitive analysis that honestly names the dominant alternative (including "doing nothing" or "using a spreadsheet") and explains why customers will switch is more useful to an investor than one that demonstrates the founders have put their logo in the top-right corner.
The structure that tends to work
There is no single correct pitch deck structure, but there is a sequence that experienced investors generally find navigable: problem, solution, why now, market size, product, business model, traction, team, ask. The "why now" slide is one that many founders omit and that investors consistently cite as valuable. It's the question of what has changed to make this the right moment is one of the more useful filters between a good idea and a fundable business.
The ask slide is worth more thought than it usually receives. Many decks simply state the raise amount without contextualising it. What investors want to understand is how the capital will be deployed and what it is designed to achieve specifically, what milestone the raise is intended to reach and why that milestone represents a materially de-risked version of the business. A raise that has a clear next milestone attached is easier to evaluate than one that is simply a number.
What this means for founders
The practical upshot of the research is that a pitch deck is not primarily a document for communicating everything about the business. It is a document for generating a conversation. The goal of the deck is a second meeting, not a cheque and the second meeting is where the depth that the deck cannot contain gets explored. Founders who try to resolve all investor uncertainty through the deck itself tend to produce documents that are comprehensive, dense, and much longer than the three-minute attention window can absorb.
The venture data room inside VentureFactory is built around this principle. It's organising supporting materials in a format that lets investors go deeper on the areas that interest them after the deck has opened the door, rather than requiring founders to front-load everything into the pitch document itself.
Your pitch deck opens the door. Your evidence gets you through it. Build your pitch and organise your supporting materials in VentureFactory's Venture Data Room. Start free, no credit card required